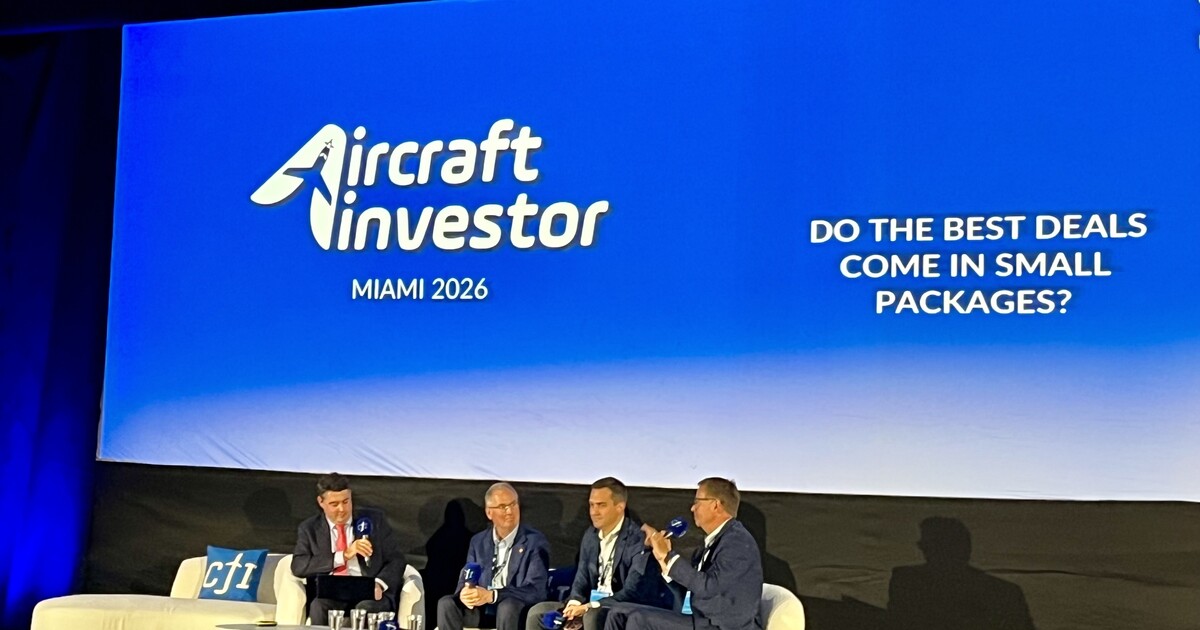
The share of preowned business aircraft purchases financed with debt has climbed to 38% from about 30% pre-Covid, even as interest rates have roughly doubled, according to lenders speaking on Monday at Corporate Jet Investor (CJI) Miami 2026
Jim Blessing of AirFleet Capital, citing JetNet data for the U.S., said the increase has added about $1.5 billion in transaction volume to the business aircraft finance sector. He appeared on a panel—“Do the Best Deals Come in Small Packages?”—along with Christopher Lee of 1st Source Bank and Michael Smith of Scope Aircraft Finance, moderated by Alasdair Whyte of Aircraft Investor/CJI. All three panelists serve on the National Aircraft Finance Association board.
Financing Gains on Cash
Lee said borrowing has increased alongside rates over the past 12 months. “As rates have gone up, the amount of people financing also has gone up,” he said.
He described cash as a longtime competitor to aircraft lenders and said higher rates are leading more buyers to weigh the cost of tying up capital in an aircraft. As a result, he said, “We’re having a lot more conversations with CFOs about the benefits of leverage versus the opportunity costs of using all that cash in the airplane.”
Asked about operators’ reports of difficulty obtaining bank financing, Lee responded, “I think they’re talking to the wrong banks.” He noted that all three panelists’ firms are actively lending and said he believes this has been “a good year for a lot of us in the room.”
Blessing said obstacles typically arise when an operation is still in its early stages and lacks the financial track record that traditional lenders require, leaving a bank to underwrite a business plan rather than an established profit-and-loss history. In those cases, he recommended bringing in outside equity or a silent partner, noting that such companies can have growth that “exceeds the capacity of a traditional P&L, balance-sheet lender.”
The Case for Smaller Loans
Whyte raised a common objection among bankers: that smaller transactions are not worth the effort. Smith countered, “A $7 million PC-12 loan is still a $7 million loan. Smaller is a relative term.”
He said spreading risk across many smaller loans improves residual value stability and shields a portfolio from the swings in outstanding balances that occur when large aircraft loans pay off. The result, he said, is “consistency in balances, which creates consistency in returns on the assets.”
Lee acknowledged that a single large deal can rapidly expand a bank’s exposure, but he said smaller transactions allow a lender to build a client relationship early. “Sometimes a client will grow into a larger aircraft and become a much larger relationship with the bank,” he said.
He also pointed to market cycles. Owners who step up from a Cirrus SR22 to a turboprop or light jet during strong markets, and sometimes stretch into a midsize jet, often return to turboprops and light jets in downturns, a pattern Lee said dates to 2001.
Owner-pilots and Ownership Structures
Blessing said owner-flown aircraft buyers are quite different from corporate purchasers. A first-time buyer of a new SR22T, for example, often requires guidance beyond financing, including help with tax structuring and insurance.
These buyers also “love to talk about their airplanes,” he said, whereas a CFO acquiring a Citation CJ4 is typically “just not really interested in the airplane.” Smith added that owner-pilots are usually the decision-makers and want to close quickly so they can take delivery.
Lee said loan contracts for small and large aircraft are virtually identical, with credit quality, collateral, and debt service coverage ratios varying from deal to deal. Smaller transactions, however, can take longer because those clients often have less experience.
Ownership structures also become more complex as aircraft size increases, according to Blessing. A Cirrus purchase may involve a single-member LLC, while a HondaJet may sit behind as many as four LLCs plus trusts. He added that most buyers of Cirrus, Cessna, Beechcraft, and Pilatus aircraft still register them in an entity and rely on aviation tax consultants.
More In Finance, Taxes, Insurance